We've given JURAdvoc a new look, learn more.
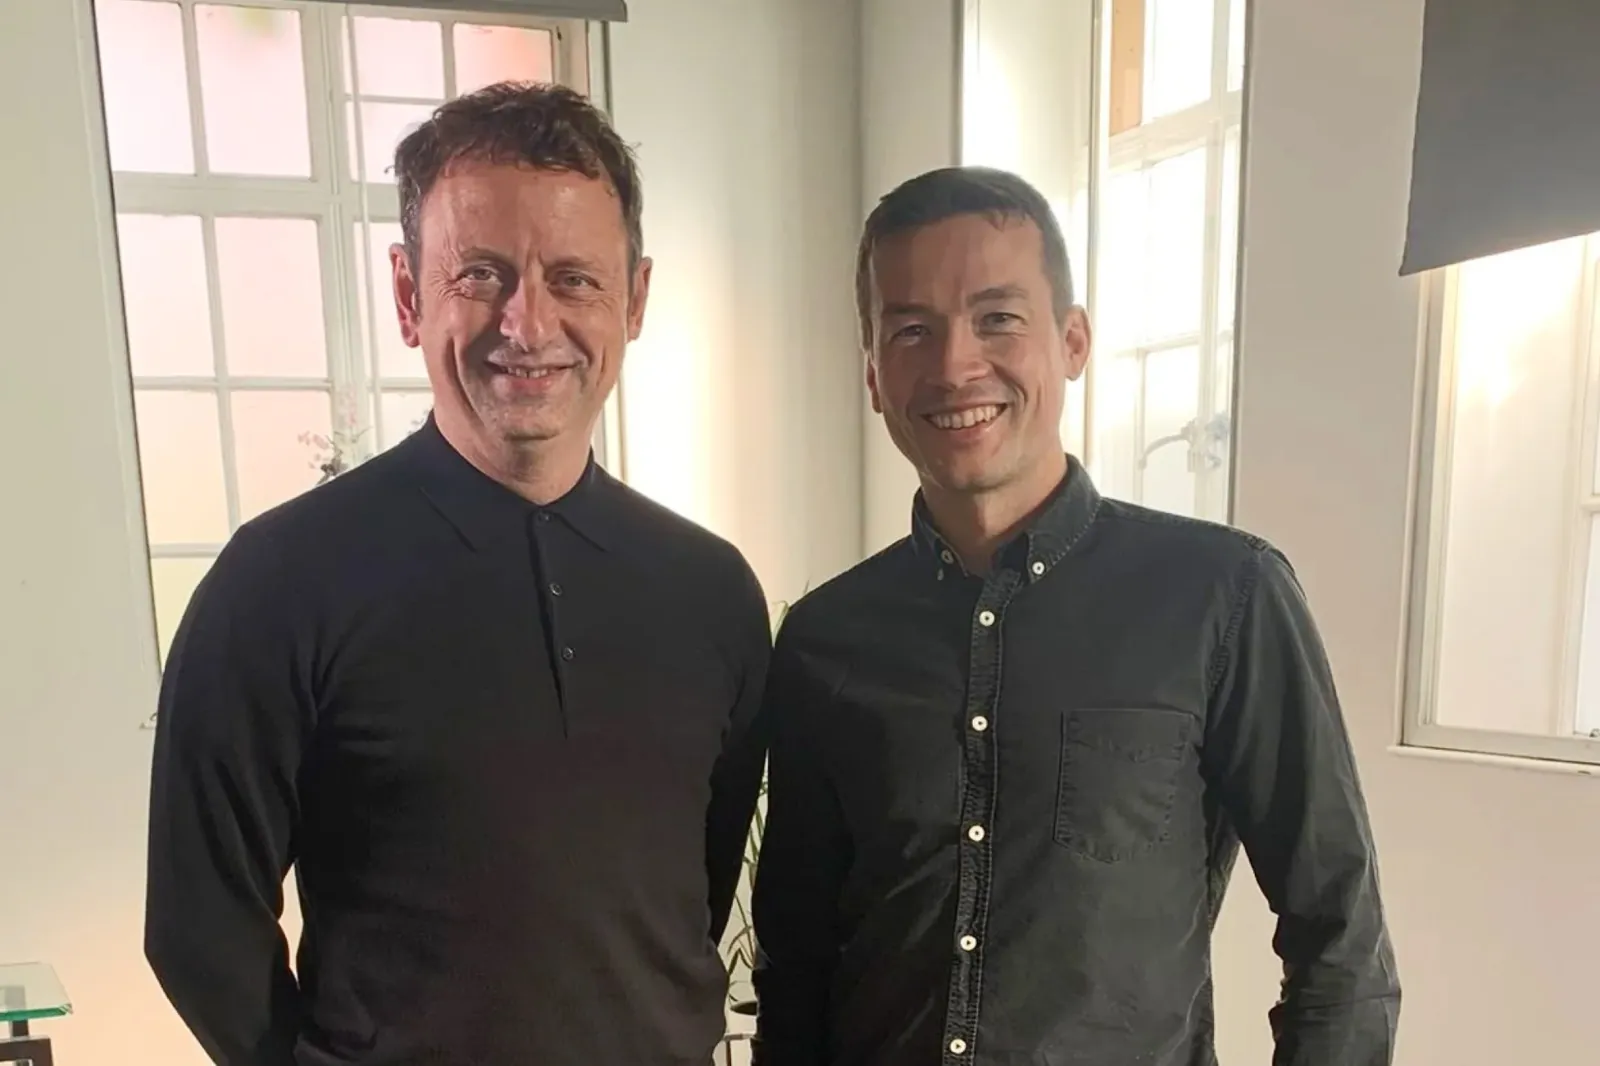
JURAdvoc’s Stuart McFadden on BBC’s The One Show
Published November 23, 20220 min read

authorised push payment fraud
JURAdvoc was on BBC’s The One Show today appearing in the Watchdog segment (for all the right reasons) to talk about bank’s responsibilities when it comes to unauthorised payments. This isn’t our usual area as we normally deal with authorised push payment fraud but nevertheless, we are experts on all things fraud!
What is an unauthorised payment?
It’s essentially when a transaction happens that you didn’t consent to. For example, your card is used without your permission or somebody steals your phone and uses it to send money.
What are some examples of unauthorised transactions?
There are many ways in which fraudsters are able to make transactions without your consent as shown on Watchdog. Here are some examples; but there are many, many clever ways that fraudsters find loopholes in the bank’s systems.
Example 1: Shoulder surfing
The low-tech and traditional way of doing this is by watching over your shoulder at a cashpoint as you enter your PIN and then later stealing your card. However, we increasingly see people use the same PIN on their phone as their bank card or their mobile banking app pin. Fraudsters will again watch people enter their phone PIN over their shoulder.
Example 2: Remote access
We often see cases referred to as “safe account scams” where callers pretend to be from your bank and convince you that your account is compromised. Other similar scams include people pretending to be from other organisations such as Amazon or HMRC. The commonality is that they get remote access and, once you are logged into your bank, they steal the money by sending it from your account or they make transactions that they trick you into approving.
Example 3: Apple Pay scam
We’ve seen cases where in advance, the caller has managed to get many personal details from the customer. They pretend to be from their bank and tell them to cancel their card and that a new one is on the way. They manage to do a clever trick where they tell you to set up Apple Pay temporarily while you wait for your new card and in doing so, convince you to give them some access codes for the Apple pay registration. In reality, they are setting up your account on their own phone alongside Apple Pay and will then go on a spending spree.
What protection do you have if an unauthorised payment is made on your account?
Put simply, banks are supposed to refund people by the end of the next business day unless they can show that the customer has been grossly negligent, is acting fraudulently or authorised the payments. The burden of proof is on the bank and not the customer to do this, but, you need to cooperate fully with the bank's investigation.
Gross negligence is a high bar for the bank to prove and it has to be really negligent such as writing your PIN on a piece of paper and leaving it in your wallet next to your bank card. JURAdvoc has seen many examples of banks incorrectly applying the gross negligence standard to people who were not at fault for what happened.
Are banks dealing with unauthorised payments correctly?
Unfortunately, we frequently see cases where the banks haven’t refunded a customer when they should have. Generally, we think this is where:
- The chain of events is complicated and the banks haven't carried out a thorough enough investigation
- We also see that some of the new payment service providers or banks have a poorer understanding of their regulatory obligations
How to protect yourself
- Never give out any banking details or access codes
- If anyone calls you pretending to be from your bank or any other official bodies, hang up and call back on the number of the card or on their official website. Remember, fraudsters can spoof real organisation’s numbers and pretend to call you from them
- Don’t use the same PIN on your phone as your banking app
What if you’ve been a victim of fraud?
Authorised or not, you should report any fraud to your bank first. If they don’t refund you, JURAdvoc can help you get your money back from your bank and you can fill in our fraud refund claim form for a free consultation. Our fees are fair, industry-lowest, and straightforward. We charge an upfront fee, which is refunded if your claim is unsuccessful. Our fee is 10-15% (+VAT), charged upfront and refunded if your claim is unsuccessful. There are no hidden costs, and the fee is refunded if we are not successful. To see your potential fee, use the fee estimate calculator on our fees page and review the fee banding and example illustrations.
Remember you don’t need to use a company like JURAdvoc, you could work your case yourself for free! If you’d like to get a refund yourself, you can do this by following our bank transfer refund guide.